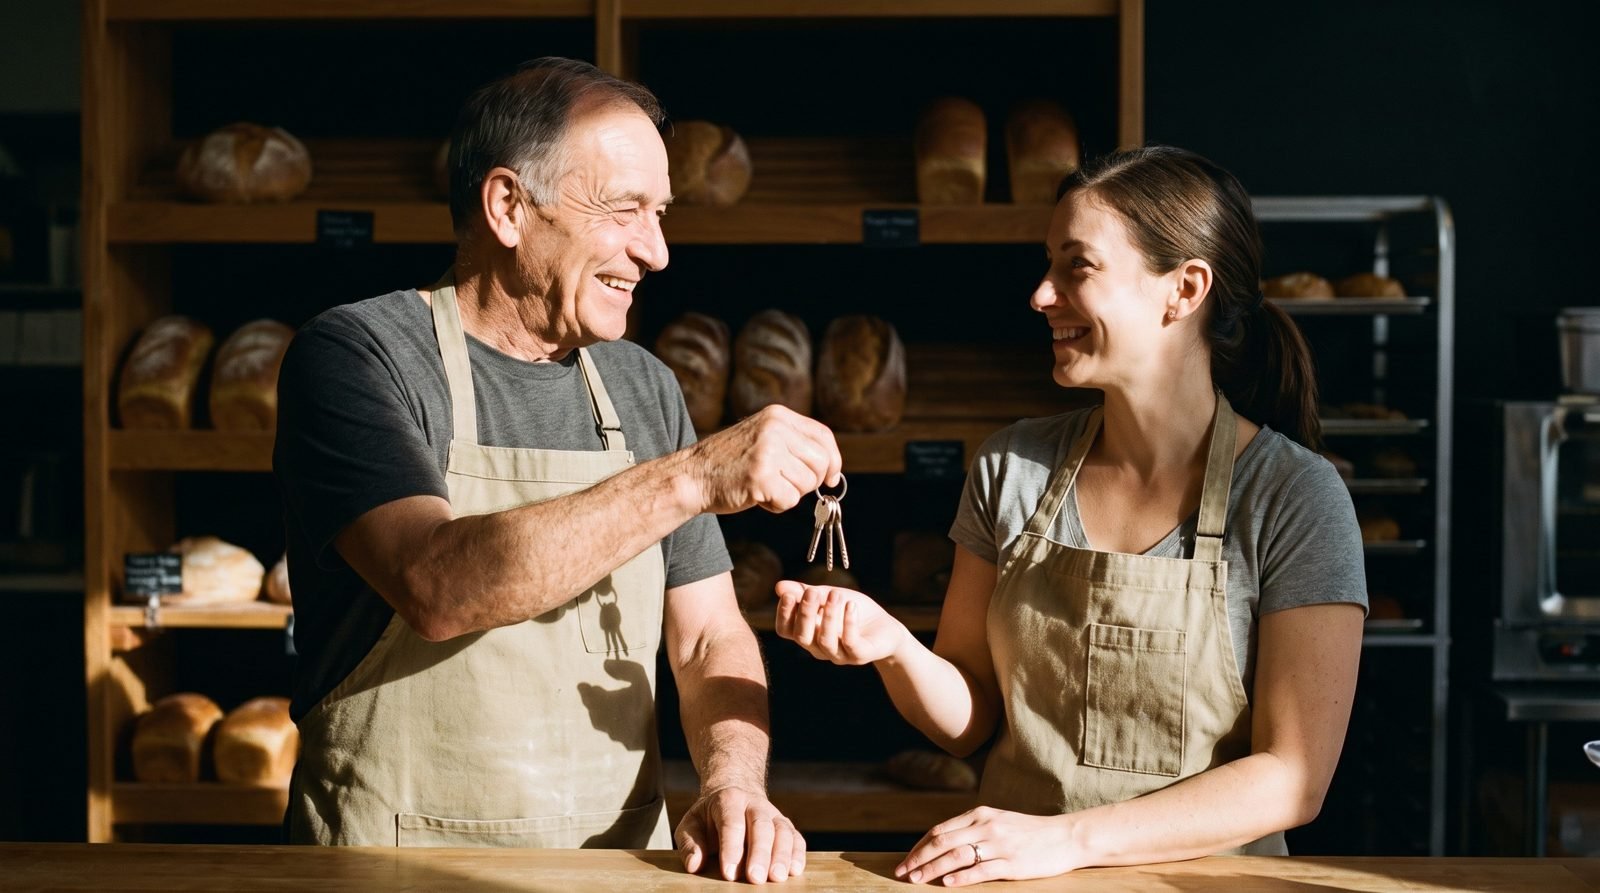
Handing Over the Keys: How to Pass Your Business to the Next Generation
A lot of Canadian business owners are getting ready to step back. In October 2026, the Canadian Federation of Independent Business (CFIB) said nearly two out of three small business owners plan to leave their business. Many of them hope to hand it to a son or daughter. Getting ready for that day is called family business succession planning.
Tom owns a bakery. He came to see Dr. Major with a big question.
A Conversation About Family Business Succession Planning
Tom: I have run this bakery for 35 years. I want my daughter, Emma, to take over. Where do I even start?
Dr. Major: Great question, Tom. Think of it like a relay race. You do not just drop the baton and walk away. You run beside Emma for a while, then you pass it smoothly. That plan is called a succession plan.
Tom: Do I really need it written down? Emma knows the shop.
Dr. Major: Yes, write it down. Many owners keep the plan in their head. Then something surprising happens, like an illness, and nobody knows what to do. A written plan says who takes over, when, and how.
Tom: How long does this take?
Dr. Major: Longer than most people think. Family handovers can take several years, sometimes up to ten. Starting early gives Emma time to learn and gives you time to save for retirement.
Tom: Emma is a great baker. But she has never done the payroll or talked to the bank.
Dr. Major: That is normal. Being good at the work is not the same as running the business. Let Emma shadow you. Give her one new job at a time, like ordering supplies, then paying staff, then meeting the bank. You stay close by, like a coach on the sidelines. By the time you leave, she has already done every job at least once.
Tom: What if she makes a mistake?
Dr. Major: She will, and that is okay. It is much better for her to make small mistakes while you are still there to help.
What About Taxes When You Pass the Business to Family?
Tom: I heard selling to family used to cost more in tax.
Dr. Major: You heard right. In the past, selling your company to your own child could be taxed more than selling to a stranger. The rules changed. Now, if you follow the steps, a real family transfer can be taxed like a normal sale. The steps are strict, though. You have to actually hand over control within a set time. That is where an accountant helps.
Tom: What if my son, Jake, wants a share too? He does not work at the bakery.
Dr. Major: That is very common. Fair does not always mean equal. Emma might get the bakery, and Jake might get other things, like savings or life insurance money. The key is to talk about it as a family now, so nobody is surprised later.
Tom: And if one day nobody in the family wants the bakery?
Dr. Major: Then you still have choices. You could sell to a key employee or to an outside buyer. A good plan works no matter who ends up holding the keys.
Tom: Okay. What should I do first?
Dr. Major: Three things. One, find out what the bakery is worth. Two, have a family meeting so everyone knows the plan. Three, update your will so it matches the plan.
Quick Recap
- Start early. A family handover can take years.
- Write the plan down: who, when and how.
- New tax rules can help family transfers, but the steps are strict.
- Fair is not always equal. Talk with all your children.
- Get your business valued and update your will.
Ready to plan your handover? Major Tax & Accounting, CPA helps business owners in London, Ontario and across Canada with estate, trust and succession planning. Book a 15 minute call today.
This article is general information only. It is not tax, legal or financial advice. Every family and business is different, so please speak with a qualified professional about your own situation.